


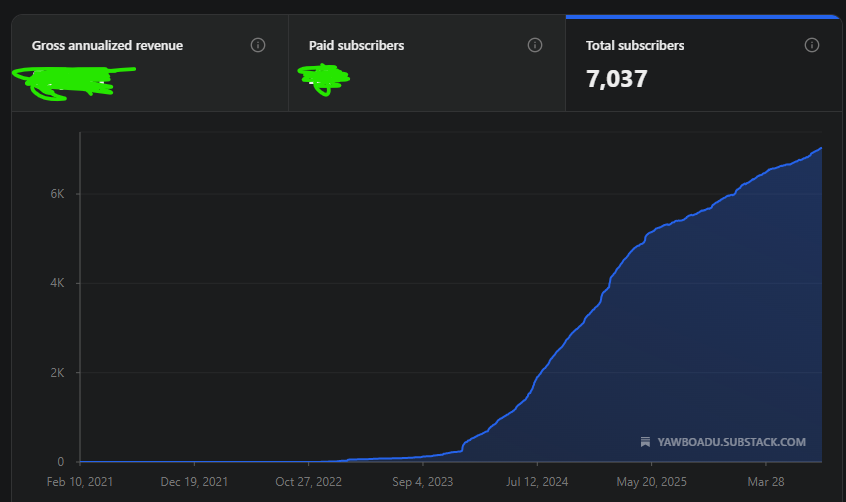
7K+ subs! Thank you all for your support. To celebrate this milestone, I opened the floor for a Q&A, and some of you DM’ed me your questions.
Q1: How was the wedding? What kind of Wedding was it?
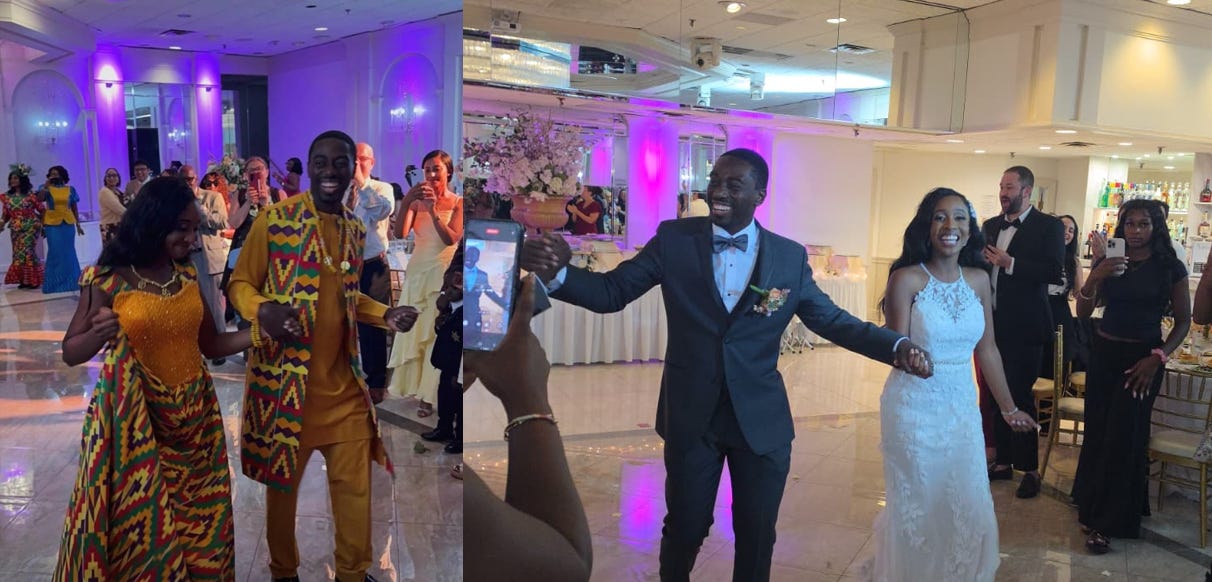
The wedding was amazing. As many of you know I’m Ghanaian (Akan ethnicity, under the Ashanti tribe), while my wife is Haitian. We both wanted our heritages in the room, so we took a Western-style wedding and infused it with Ashanti & Haitian cultural elements.
Q2: What Ghanaian Cultural Elements did you include in your Wedding?
I did kete dancing.
Historically, Kete was a royal-religious Ashanti ritual used to communicate with chiefs, spirits, and ancestors. But its modern, widespread popularity in Ghana traces back to Ghana’s 1st Prime Minister & President, Kwame Nkrumah (1957-1966).
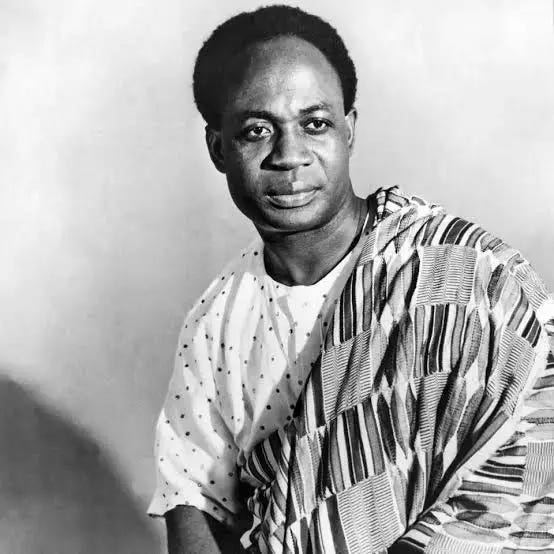
Kwame Nkrumah made many mistakes, in fact, many Ghanaians do not tolerate any criticism of him at all. He is called “Osagyefo” or “Redeemer” in Twi (A dialect of the Akan language). But, I’ll discuss more in deep detail when my Substack roadmap finally hits Ghana. (Programming note: I plan to finish Nigeria this year, then Kenya. Then I’ll make you guys vote next).
But one thing Nkrumah got absolutely right was forging a strong sense of Ghanaian Nationalism.
I don’t want to overstate this. Ghanaians will still identify with their ethnicity and have voting patterns based on ethnicity (for example: many Akan-speaking groups like Ashanti, Akyem, Kwahu, Akuapem will vote NPP while Ewe, Guan, and many Northerners vote NDC) but compared to other African countries, there’s never been a sense that people cannot live together. Unlike Sudan, Nigeria, Uganda or other African countries where ethnicity was historically a backdrop to war or mass violence, Ghana hasn’t had anything on that scale despite being a mix of ethnicities.
To bridge the diverse tribes (Ewe, Akuapem, Ashanti, Fante, Gonja, Ga, etc.), Nkrumah did many programs to downplay tribalism. This was difficult since some ethnic groups have historical animus against each other, especially against the Ashanti which was the historical “regional imperialist”. In fact, the Fante, who basically speak the same language as the Ashanti, but with a different dialect, teamed up with the British against the Ashanti.
His government established the Ghana National Dance Ensemble and the Arts Council of Ghana. These institutions collected, staged, and popularized regional royal dances for national audiences. Kete was integrated into university curriculums and school competitions, which removed the traditional hereditary requirements to learn it.
By the 1980s & 1990s, the diaspora and upper middle class had adopted Kete for weddings and celebrations.
The point is, I give Nkrumah’s government credit of repurposing an ancient royal-religious ritual, associated with one tribe, into a celebration of national unity.
Q3: Does your wife read your substack? What languages does she speak?
She is incredibly supportive of my Substack, but she doesn’t actually read my articles. She doesn’t feel the need to since she hears me narrate them aloud while I’m drafting. She speaks English, Haitian Creole, French and Spanish.
Q4: Where did you go on your honeymoon?
We went to France, which has always been her dream destination to go for a honeymoon.
We went to Paris, Versailles, Nice, and a couple other places. Now, on to more traditional Yaw substack programming.
Q5: Why does a country borrow in dollars if it can create its own currency?
At first glance, this seems really weird. If you are in a 1st world country, your country generally borrows in its currency. America borrows in dollars, UK borrows in pound sterling, and most countries in the European Union borrow in euros.
So if Pakistan has Pakistani rupees, Zambia has kwacha, and Sri Lanka has Sri Lankan rupees, why would government voluntarily borrow in dollars, yen, or euros? Especially when borrowing in a foreign currency can be dangerous.
Pakistan gives us a perfect example. In 2021, the Pakistani government went to international investors and basically said: “Give me $1B today by buying my $1B eurobond (which is dollar denominated), and I promise to pay you 7.4% interest per year, and I’ll give you your $1B back in 10 years.”
When Pakistan issued that eurobond, Pakistan received $1B (~160B rupees at that exchange rate). Right now in August 2026, the Pakistani rupee has depreciated sharply, now that same $1B principal represents 280B rupees.
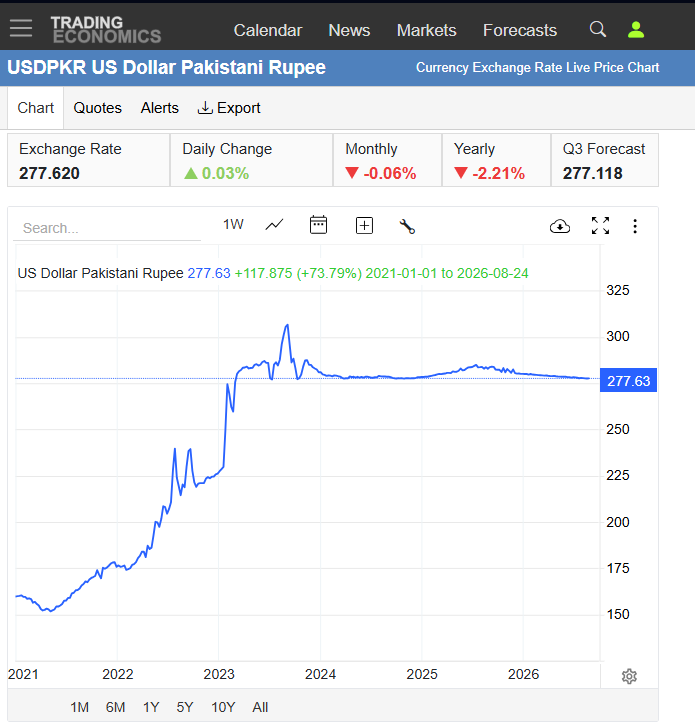
If you borrow 160B rupees, pay interest, and then have to pay back 280B rupees, your principal is nearly up 75% in rupee terms. On top of that, the interest itself is getting more expensive in rupees every year its paid.
Pakistan collects revenues in rupees but has to pay debts in dollars. If the rupee depreciates to the dollar, the domestic currency cost of Pakistan’s foreign debt rises with it.
So why would Pakistan willingly take that risk?
There are several reasons, but I’ll just discuss two today:
Sometimes the country actually needs foreign currency
Sometimes borrowing in dollars can be much cheaper than borrowing in local currency
Even then, dollar loans are not a magic potion. But to understand those constraints, we first need to understand what actually happens when a government borrows in its own currency.
5.1 How does a government borrow in its own currency?
Let’s look at Pakistan. (And by the way, everything that I am saying about Pakistan right now is also true about the United States or Switzerland. The differences will come later).
Pakistan’s currency is the Pakistani rupee. If the government needs money, it issues rupee bonds, and then a commercial bank in Pakistan, like Habib Bank Limited (HBL), buys the bond with its settlement reserves.
HBL’s settlement reserves are transferred from HBL to the Pakistani government’s account at the Central Bank.
Where do HBL’s settlement reserves come from? From Pakistan’s Central Bank, the State Bank of Pakistan (SBP), which provides settlement reserves using two different tools.
Outright Purchases: The Central Bank buys commercial banks’ rupee bonds with settlement reserves, basically swapping a bank’s bonds for cash.
Repurchase (Repo) Market Operations: HBL hands over rupee bonds to the Central Bank as collateral and borrows settlement reserves from them, which it can then use those borrowed settlement reserves to buy rupee bonds. Then, HBL agrees to buy back those rupee-bonds from the Central Bank in a few days or weeks later at a slightly higher price. The difference in price is the interest rate the central bank charges for the settlement reserves. If the bonds are bought back the next day, that’s called the overnight repo rate.
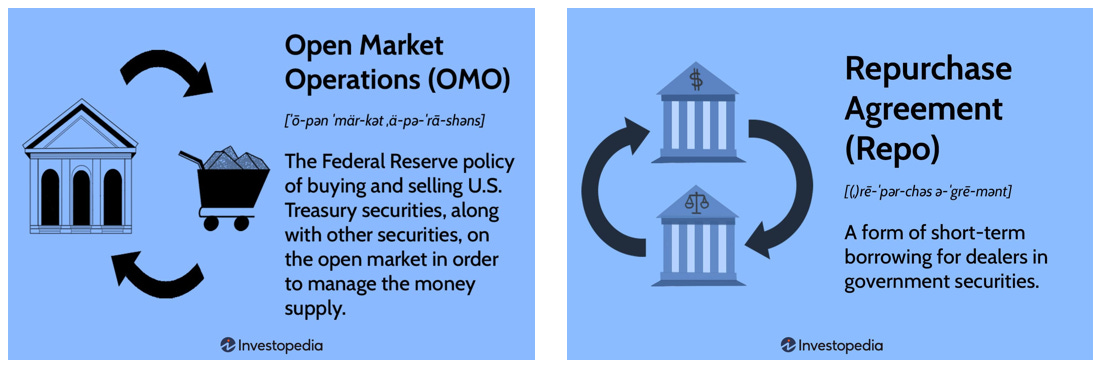
As a result, a central bank that issues its own currency cannot run out of settlement reserves denominated in that currency. AKA, central banks can print settlement reserves. But printing money is NOT the same as printing value.
Making financial claims in your own currency (issuing debt) is easy. But creating real resources, foreign exchange, willing savers, and a stable demand for those financial claims isn’t.
This probably sounds abstract, so let’s build from the ground up.
5.2 Is a developing country limited by bank deposits from domestic customers?
Not really. A commercial bank does not necessarily need to have enough deposits from customers before it lends.
Let’s say Pakistan’s government sells a 100M-rupee bond to a Pakistan commercial bank (HBL). HBL buys the bond using its settlement reserves, which get transferred to the treasury’s reserve account at the central bank. Now the government has 100M rupees to spend for military corruption paying a construction company. The treasury now tells the central bank to transfer its 100M in reserves to the construction firm’s bank account (Askari Bank). Once that clears, the increment on Pakistan’s banking system looks like this:
Assets:
+100M government bond that a commercial bank, HBL, bought
Liabilities:
+100M deposit belonging to a construction firm’s commercial bank account at Askari Bank
The government deficit created a financial asset that we call a bond. The government’s deficit literally created new money in the private sector.
You said reserves before… Do banks have reserves?
Yes, commercial banks have two tiers of money:
Tier 1: Bank deposits (Retail money): This is what you, I, and the construction firm use in commercial banks. In U.S. it would be a bank like Citi, Wells Fargo, or Capital One. In Pakistan it would be HBL or Askari.
Tier 2: Settlement Reserves (Wholesale money): This is special digital money created by the Central Bank (like the Federal Reserve in the U.S. or SBP in Pakistan). Only banks and the government can hold settlement reserves. Settlement reserves are the cash used by banks to settle payments with each other. If you wire $100 from Bank A to Bank B, Bank A lowers your deposit balance by $100, and then uses the Central Bank’s clearing system to send $100 in settlement reserves to Bank B.
You are probably thinking “Wait… Bank A pays Bank B using reserves? Why doesn’t it just use your money when you wire $100?”
Banks don’t just wire your money to each other. We need to understand what a bank balance is. “Your money”, the money you deposited to a bank, is actually the bank’s debt. A deposit is one bank’s IOU. A bank doesn’t put that cash in a box with your name on it. Instead, Capital One adds $100 to its asset column, and writes a $100 IOU to you in its liability column.
When you open your banking app and it says $100, that’s the bank’s promise to pay you $100 if you ask for it. Your money in your checking account or savings account is really you lending to a bank and then you receive interest.
Bank A can’t pay a Bank B using its IOU. What if Bank A goes bankrupt? Bank B wants to paid in a risk-free claim. That’s the whole point of Central bank settlement reserves.
The Central Bank sits above all the commercial banks. Just like how you have an account at Capital One, Capital One and Bank of America both have accounts at the Central Bank. The digital money in those Central Bank accounts is the reserves I mentioned before. Reserves are IOUs from the Central Bank itself, AKA the Commercial Banks are lending to the Central Bank. Because the Central Bank prints the money, its IOUs are considered risk-free.
So when you hit “send” to wire $100 to your buddy, this is what actually happens:
Capital One deletes $100 from your account (canceling the “loan” you gave it, which is your checking account).
Capital One sends $100 in its reserves via the Central Bank to Bank of America
Bank of America receives those reserves, and types $100 into your friend’s account (creating a brand new IOU to your friend).
I hope you get by now that there isn’t some warehouse of cash that became empty. If a bank’s settlement reserves become scarce, the central bank can just create reserves. So now you understand that banks are not mechanically limited by pre-existing customer deposits (retail money); worst case, the central bank can just create settlement reserves (wholesale money). Pakistan’s Central bank can make rupees, Ghana’s central bank can make cedis, and America’s central bank can make dollars.
But, what Pakistan or Ghana’s Central bank can NOT do is create dollars.
#5.3 So if there’s no mechanical constraint of banks running out of cash, what’s the catch?
The Philippines or Pakistan can issue 100M pesos or rupees, but imagine if The Philippines, Pakistan, or any other country borrows 100M again, and again, and again, and again…. From all of this, the banks and pension funds accumulate more government bonds.
Then the government will use those bonds to pay for goods and services from private firms or state-owned enterprises (SOEs) or just give money to households, so then the private firms, SOEs, and households will have more money in their bank deposits.
Now here’s where the constraints come in. The question is:
Do those banks and pension funds want to hold all these government bonds at the existing government bond interest rate?
AND
Do businesses, corporations, and households want to hold their local currency deposits at their existing bank interest rate?
Because if banks, businesses, and households don’t, something adjusts. There’s three types of adjustments that take place:
Inflation (The deposit adjustment): If households have more cash than they want to save, they try to spend it. They want cars, houses, groceries, and more. If the economy cannot produce enough real goods and services to absorb that spending, then prices rise. The value of the currency weakens compared to goods and services.
Rising Interest Rates (The bond adjustment): If banks and pension funds feel overwhelmed by the sheer volume of government bonds being issued, they will demand a higher rate of return to keep buying them. The bond price will fall since there’s lower demand, and as a result the government will have to promise a higher rate of return for banks and pension funds to keep buying them. Since the domestic government bond yield is the benchmark rate for the domestic economy, if domestic government bond yields rise, then interest rates will rise across the entire economy.
Currency Depreciation (The Exchange Rate Adjustment): If people and businesses have too much local currency and have a huge demand for foreign goods, then they might try to trade their local currency for dollars or euros. The mass selling of local currency to get dollars or euros then weakens the local currency compared to the dollar/euro.
The government can create infinite local money, but it can’t force households, businesses, and traders to value that money at the same rate. The ultimate constraint on government borrowing isn’t “do we run out of deposits”, but rather it is the households, banks & pension funds, and traders’ willingness to absorb that newly created money without triggering more incremental inflation, higher interest rates, or a weaker currency. If the developing country’s government wants to continue creating money without having all 3 of those issues (or capital controls), that’s exactly where foreign borrowing comes in.
Now, foreign borrowing isn’t a magic pill. Foreign borrowing doesn’t delete these constraints. But it can relieve two of them temporarily: it brings FX into your country to import goods and reduce the amount of financing the domestic bond market needs to absorb.
#5.4 Why Developing Countries borrow: The country actually needs dollars
If Sri Lanka wants to pay Sri Lankan teachers, the government can issue 100K Sri Lankan rupee-bonds, some domestic banks and pension funds buy the bonds, and then the government can pay the teachers. That’s a domestic financial problem.
But if Sri Lanka needs to import diesel, Sri Lanka buys via a Singapore-based commodity firm like Vitol Asia. The commodity firm, however, does not accept Sri Lankan rupees as payment. Not just diesel, Sri Lanka also can’t use rupees to import medicine, industrial machines, or pay off foreign loans. Sri Lanka will need foreign exchange (FX) for that.
But here’s the constraint, Sri Lanka CANNOT create Foreign Exchange (FX). Sri Lanka’s central bank can’t create US dollars, only the Federal Reserve can. Sri Lanka’s central bank can’t create yen, only the Bank of Japan can.
So Sri Lanka has to obtain FX (usually US dollars). How can Sri Lanka get dollars? It can through
exports
tourism
remittances
Foreign Direct Investment (a foreigner goes to a Sri Lanka bank, exchanges their euros for Sri Lankan rupees, now the Sri Lankan bank has FX while, the foreign investor buys 10% ownership or more of a Sri Lankan asset).
Portfolio Investment (a foreigner goes to a Sri Lankan bank, exchanges their euros for Sri Lankan rupees, then buys stocks (under 10% ownership) or bonds in Sri Lanka)
OR Borrow in foreign currency (they usually borrow in USD dollars via a badly named debt instrument called a eurobond)
That’s why Sri Lanka borrows in foreign currency… To import foreign goods.
If it can’t do any of that, it can spend its foreign reserves from its central bank. That’s Sri Lanka or any developing country’s hard constraint. For foreign reserves, you really should think of it like a warehouse of cash that can be depleted.
Sri Lanka ran into this constraint in 2022. Sri Lanka had $7.5B in reserves in 2020 and had $1.6B in reserves by Nov 2021.
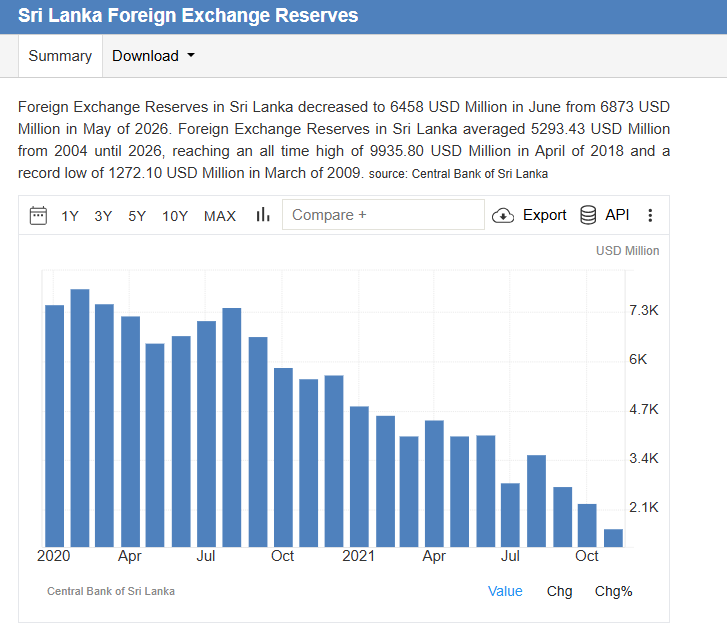
Now, knowing that Sri Lanka had $1.6B in reserves remaining is a meaningless stat unless you know how much Sri Lanka hemorrhages on FX per month. Like is $1.6B a lot for Sri Lanka?
To contextualize, we’d look at months of reserves by import coverage. When we use this, we see Sri Lanka was in an awful spot. Sri Lanka went from 3 months of import coverage in 2020 to 30 days of import coverage in 2022.
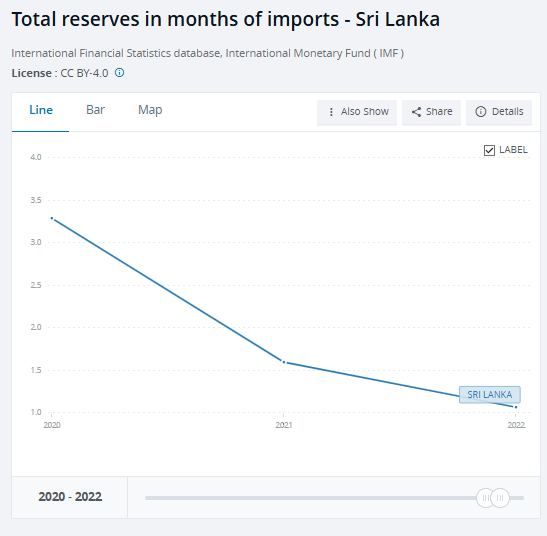
When you have less than 3 months of FX, you are in crisis territory. Why? Well, international trade doesn’t happen overnight. When a country orders coal/wheat/oil, it operates on a logistical timeline. It takes time to negotiate a contract, have a cargo ship travel across the ocean, and unload cargo. To facilitate this, domestic banks issue letters of credit to foreign suppliers, promising that the dollars will be there when the ship arrives.
If a country has under 3 months of reserves, foreign banks and suppliers pencil out the math and realize the country might run of out of dollars/yen/euros before the ship even docks. They may stop accepting letters of credit, meaning the country literally can’t import new goods.
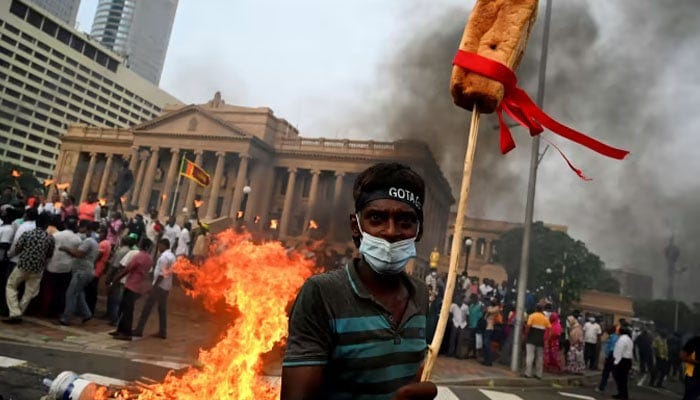
In 2022, Sri Lanka couldn’t even import essential imports like fuel and energy, and Sri Lanka defaulted on foreign debt. Notice how Sri Lanka wasn’t suffering from a shortage of rupees. Instead, Sri Lanka lacked “claims on goods produced outside Sri Lanka”, which is what dollars represented. Sri Lanka lacked dollars…
So what about the counterfactual? What if Sri Lanka said “I’ll never borrow in dollars!”
That’s fine. But then Sri Lanka’s foreign budget constraint becomes harder. Because imports, foreign interest payments, and external payments, must be financed by exports, tourism, remittances, FDI, or foreign reserves drawdowns.
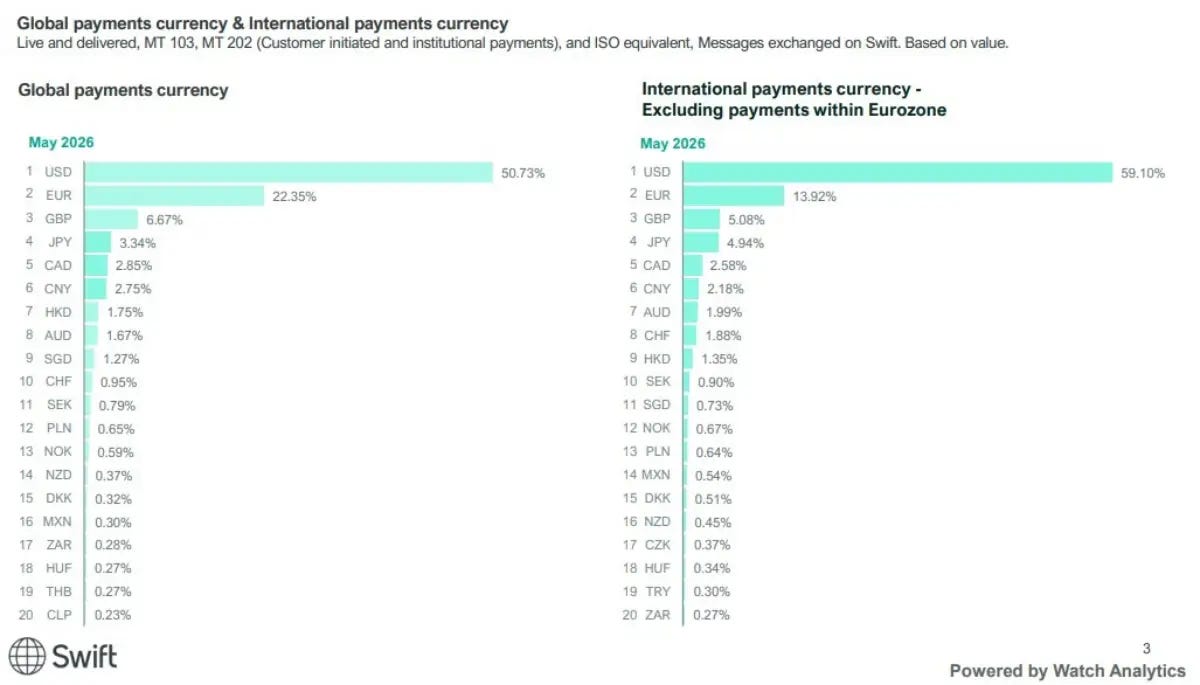
If Sri Lanka wants to import $20B of imports, but only has $10B in sustainable FX income, it can’t fill that $10B hole by printing rupees. No one takes rupees as international payment. The top 5 currencies for settling trade as of May 2026 are dollars, euros, pounds, yen, and the Canadian dollar.
If Sri Lanka prints rupees, then Sri Lankans receive more rupees and exchange rupees for dollars. When you sell your rupees for dollars, you put downward pressure on the rupee, and put upward pressure on the dollar. Then three things could happen:
Central Bank intervention: The Central Bank will sell dollars and buy rupees to maintain the exchange rate so the rupee doesn’t get weaker (Until it runs out of FX).
Allow Depreciation: The government could not interfere at all. With so many people exchanging rupees for dollars, the rupee depreciates until imports become too expensive
Capital/Import Controls: The government bans selling rupees for dollars, or will ban certain imports.
The point is a country can’t indefinitely buy more from the world than it has the international cash to pay for. Foreign borrowing allows developing countries to temporarily escape that constraint by saying “lend me dollars today, and I'll give you dollars tomorrow”. That’s all what foreign loans are.
If lenders think the country won’t repay foreign debts, the country will need to borrow at prohibitively high rates or just be locked out of financial markets. At that moment, the country can only regain credit access through some combo of debt restructuring, policy adjustments, and outside financing; an IMF plan is usually part of that process.
But let’s talk about another reason why developing countries borrow in foreign loans while they still have credit access.
Reason #2 Many times it’s cheaper to borrow in dollars than to borrow in local currency
In 2012, Zambian President Michael Sata started his term and wanted a big infrastructure push.
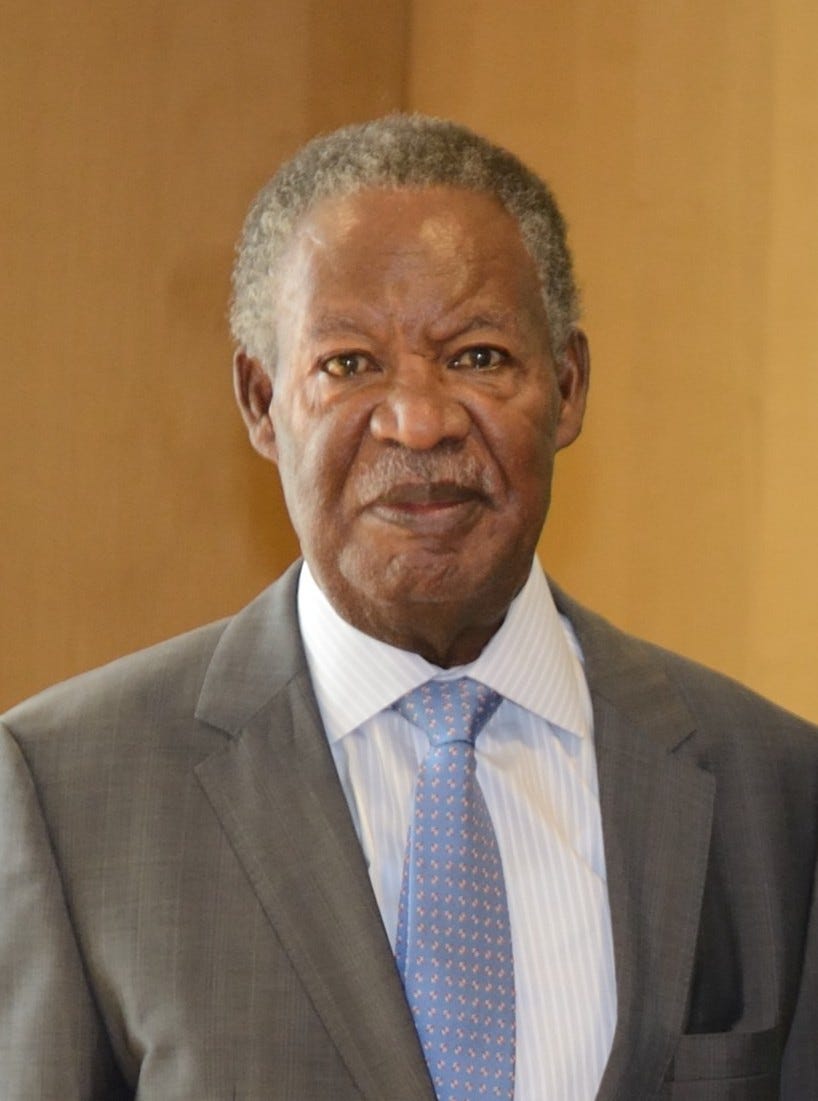
His government issued a $750M, 10 year eurobond. At auction, Zambia was able to borrow 5.6%.
The counterfactual would have been local borrowing. If Zambia issued a 10 year Zambian domestic government bond, then the government would have to borrow at 15.7%. That gap is why the finance ministry was tempted by eurobonds. The Zambian finance minister wanted to borrow relatively cheaply for energy, roads, rail, hospitals, and other infrastructure.
But of course there’s a catch. The exchange rate.
In 2012, ~5 Kwacha (or 5K old ZMK, Zambia redenominated its currency and removed 3 zeros in January 1st, 2013) was 1 dollar. In local currency, Zambia received 3.75B kwacha at a 5.6% interest rate instead of 3.75B kwacha at a 15.7% interest rate.
But for the foreign investor, they are being paid the $750M in dollars. Sadly, over 10 years, the kwacha depreciated to the dollar. This happened because over the 10 years, there was more Zambian demand for the dollar, than global demand for Zambian kwacha.
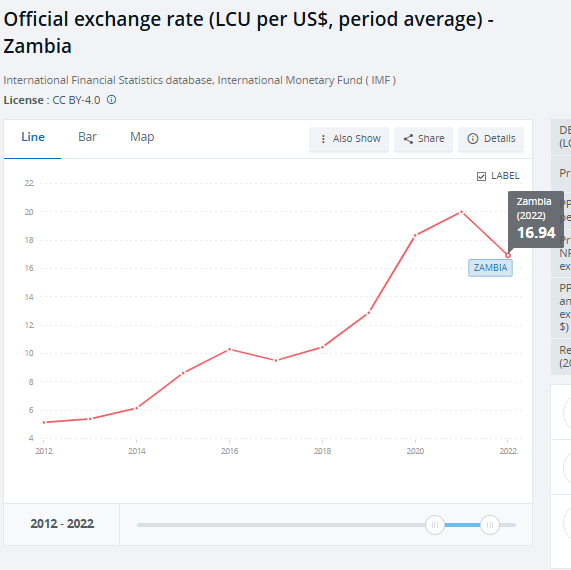
By 2022, 17 kwacha equaled one dollar. So now, that $750M in borrowed, which was 3.75B kwacha owed in 2012, ended up being roughly 12B kwacha owed by 2022.
In fact depreciation was so terrible, and the Eurobond loan didn’t lead to Zambia being able to generate enough FX to service the debt. Zambia was at emergency levels of reserves by 2017. Covid made it worse. By November 2020, Zambia missed its payment on a $43M eurobond payment and defaulted.
So in reality, the comparison isn’t really 5.6% vs. 15.7%. It’s more like, 5.6% + unknown depreciation risk vs. 15.7% locally.
Frankly, there’s a lot more to this. The depth of a country’s local financial system, banking regulations, capital controls, pension fund bond allocation, foreign participation in local bond markets, and central bank policy also affect how much a government can borrow domestically and at what cost. But I’ll discuss all that another time.
Excellent explanation of how banking works. Congratulations again on your wedding. Good looking couple. Can we expect some “micro-economists” in the future?
Note: the picture of the container ship is fake, some readers might not realise this.
I was not expecting that diversion into explaining what central bank reserves are, that's a topic I got *very* interested in following the 2008 crash. I think you overcomplicated it a bit, to restate it: reserves are like digital cash (hard currency backed by the government); while high street bank deposits and like a private currency issued by each bank, that's why other banks don't accept them. Money is like concentrated trust, that's why countries with weak institutions don't have their self minted cash trusted much by other countries or foreign companies.
Congratulations on your marriage Yaw.